
The size of Africa's productive economy is out of step with the depth of its exchanges. Africa has roughly 1,141 listed companies against more than 8,000 on NASDAQ, and Nigeria has fewer than 500,000 active CSCS accounts. Family-concentrated ownership, limited financial instruments, weak liquidity and macroeconomic instability, including exchange-rate pressure and high inflation, add to investor risk and keep the market narrow.
Size alone does not deepen a market. A market-friendly IPO puts proceeds into productive capacity rather than returning them to existing owners, attracts retail, pension and foreign investors, and offers a free float large enough for investors to buy and sell easily. It also supports active trading and price discovery, brings strong governance and timely disclosure, and encourages other companies to list.
The offer targets 10 million investors, so even 5 million would be about ten times today's base, and 1 million active investors would triple it. The public offer is only about 3.3 percent of the company, and under 6 percent with the private placement, so daily turnover, bid-ask spreads and the ability to sell on demand will show whether real liquidity follows. The nine-month results will also shape the market's early reaction.
At a valuation of about ₦65 trillion and a price-to-earnings ratio of about 12 times, the shares are not automatically overvalued, and good companies often trade at a premium. The guest's base case is a 50 to 60 percent chance that the stock does not trade below its IPO price, while weak margins or declining results could trigger a sell-off. Retail investors should only commit money they can leave alone for three to five years, avoid trading for quick gains, and understand that the stock is a risk investment, not a guaranteed return.
Watch Previous Episodes Here
What Will It Take for an IPO to Deepen a Capital Market?
The Dangote Refinery IPO has drawn unprecedented retail attention across Nigeria. But the deeper question is not whether the offer is large or oversubscribed. It is whether an IPO of this scale can genuinely deepen Africa’s capital markets and mobilise long-term capital for industrial growth.
In this episode of the Kingsgate Brief, we explore why African stock markets remain shallow, what actually makes an IPO market-friendly, and how investors should separate brand sentiment from business fundamentals.
The conversation explores:
Why African markets remain shallow, and what makes an IPO deepen a market
How to separate brand sentiment from valuation and business fundamentals
What investors should watch after listing, and why founders avoid listing
The concentration risk of large listings, and the reforms needed to widen the pipeline
The real test of the Dangote IPO, and what it means for Africa’s public markets
From Market Depth to Shared Prosperity
The real test of the Dangote IPO is not the amount raised. It is whether it expands the economy, draws more people and companies into the market, and sustains momentum after the excitement fades.
 Tune in to this episode of Kingsgate Brief, the official podcast of the Kingsgate Advisors Institute, for an insightful conversation conversation on capital markets, investor behaviour, and Africa’s public markets.
Listen, learn, and subscribe for more policy, economic, and development insights.
EPISODE SUMMARY:
The discussion examined why African stock markets remain shallow despite the presence of large private companies, and whether IPOs can help close that gap, using the live Dangote Refinery and Petrochemicals IPO as a test case. It explained that an IPO deepens a market only when its proceeds fund productive expansion, participation is broad, the free float is meaningful, and governance and disclosure are strong, not simply because the offer is large or oversubscribed. The conversation moved across the Dangote offer’s target of 10 million investors, its small tradable float, how to separate the refinery’s strategic importance and brand pull from its valuation and fundamentals, and why investors should hold for the long term rather than expect quick windfalls. It stressed that founder reluctance to give up control, listing costs, thin liquidity and macroeconomic instability are the main barriers to more listings. It also explored the role of foreign and diaspora investors, the concentration risk of listing a very large company in a small market, and the reforms needed to widen the pipeline, including fiscal incentives, stronger minority shareholder protection, and derivatives and other instruments to improve liquidity. It closed with the view that the real test of the IPO is whether it expands the economy, draws more people and more companies into the market, and sustains that momentum after the initial excitement fades.
[Dr. Oluwanbepelumi Olanubi]: Good morning, good afternoon, and good evening, everyone, from wherever you’re tuning in to join us today. This is another episode of the Kingsgate Brief, the official podcast of the Kingsgate Advisors Institute. At Kingsgate, we believe that the ideas that shape markets, policy, and development should not be trapped in expert spaces alone. They should be brought into public conversations with clarity, depth, and practical meaning.
That is why Kingsgate Brief is designed to create room for thoughtful conversations that move beyond the headlines, simplify complex issues without weakening them, and help our audience understand what these issues mean for real decisions. Through this platform, we bring together economists, market practitioners, policymakers, business leaders, and experienced professionals who can speak to the issues shaping Nigeria, Africa, and the wider global economy. Our goal is not just to inform, but also to help people ask better questions, interpret changes in the economy and markets, and make better-informed decisions.
My name is Oluwanbepelumi Olanubi, the Executive Director of the Institute, and of course, I’ll be hosting today’s conversation. But before we begin, I would also like to encourage our audience to stay connected with us. Follow our LinkedIn page, follow us on Instagram, follow us on X, where we are now also active, and subscribe to our YouTube channel. We want you to be among the first people to know whenever we upload a new episode of Kingsgate Brief. Beyond that, please visit our website to learn more about what we’re doing, the projects we’re working on, and some of the initiatives that we will be announcing in the coming weeks and months. We have quite a number of projects in the pipeline, and we’ll be making some announcements around those projects very soon. So, thank you very much, and with that, let’s turn our attention to today’s conversation.
Today, we’re focusing on a subject that sits at the heart of Africa’s economic transformation and, particularly at the time of recording this conversation, is a very important issue. We are looking at how the continent can build deeper capital markets and use public markets to mobilise long-term capital for industrial growth, infrastructure, energy, technology, manufacturing, and enterprise development.
Our topic today is “Listing Africa’s Giants: Can IPOs, Initial Public Offerings, Unlock Deeper African Capital Markets?” And we’re taking lessons from Nigeria, particularly from the Dangote Refinery. Africa is home to a large number of major private companies, including banks, telecommunications operators, energy firms, industrial groups, consumer businesses, and technology-enabled enterprises, many of which have the scale and capacity to shape national and regional economies. Yet, despite the size of these businesses, many African stock markets remain relatively shallow, with limited new listings, narrow trading activity, weak secondary market liquidity, and a significant gap between the size of private enterprises and the depth of public markets.
That gap matters because capital markets should not simply reflect economic activity. They should also help finance and expand that activity. They should provide businesses with access to long-term capital, create opportunities for investors to participate in the growth of major companies, and ultimately contribute to the development of the broader economy. The timing of this episode is particularly important because the Dangote Refinery and Petrochemicals IPO is live as we speak. And that gives us an opportunity to take what could otherwise be a conversation about one company and turn it into a broader discussion about African capital markets, using a live market situation that we can actually observe and assess.
This raises a question that goes beyond one company or another. Can a major African industrial asset be priced transparently, distributed credibly, assessed responsibly by investors, brought into the public markets with the appropriate standards, and traded in a way that contributes to deeper and more sustainable capital markets beyond the initial excitement surrounding the IPO? The Dangote question is therefore also an African question. If large African companies can successfully move from being private champions to publicly listed companies, this could expand participation in their growth, improve disclosure and corporate transparency, attract both institutional and retail capital, build investor confidence, and contribute to a broader investment culture across the continent.
At the same time, the process raises important questions around valuation, governance, liquidity, investor expectations, and the quality of the market itself. If companies are listed at valuations that do not reflect underlying fundamentals, if trading remains thin, if governance standards are weak, or if investor attention becomes dominated by short-term hype, then the listing may not necessarily translate into deeper capital markets in the long term. By the end of today’s conversation, we hope our viewers will come away with a clearer understanding of why African capital markets remain relatively shallow, what an IPO genuinely means, and why an IPO should be understood as more than simply the initial excitement around a company becoming publicly listed. We’ll also look at what investors should think about when considering IPOs, what positioning for an IPO actually involves, and what reforms may be necessary to encourage more large private companies to enter public markets and, in doing so, contribute to deeper capital markets and greater mobilisation of long-term capital across Africa.
To help us unpack all of these issues, I’m delighted to welcome Dr. Ayodeji Ebo. Dr. Ayodeji Ebo is the Chief Executive Officer of MDU Capital Limited. He brings more than two decades of experience across investment banking, capital markets, economic and investment research, portfolio management, financial engineering, and corporate strategy. Before joining MDU Capital, he served as the Chief Business Officer and Managing Director of Plato’s New by AVI Invest. He also served as the Managing Director of Afrinvest Securities Limited. At Afrinvest he previously led the firm’s investment research division and also worked within its investment banking division. Dr. Ebo has managed multi-billion-dollar investment portfolios and is widely recognised for his expertise in investment strategy, financial markets, macroeconomic analysis, risk management, and several other areas of investment and financial-market practice.
His experience across these different areas makes him particularly well placed to help us think through the IPO conversation we’re having today, not just from the perspective of one company, but also from the broader perspective of capital-market development and investment in Africa. Good morning, Dr. Ebo, and thank you so much for joining us today.
[Dr. Ayodeji Ebo]: Yeah, good morning, Doctor. It’s great to be here.
[Dr. Oluwanbepelumi Olanubi]: Thank you very much. So, we’re going to start this morning with a broader question. Why do African stock markets remain relatively shallow despite the presence of large private companies that could potentially strengthen public markets? Why do we still have this gap within the African context?
[Dr. Ayodeji Ebo]: Thank you. This is a very topical issue and a topic that I believe everyone would be interested in. When we look at the African market, I would say that there is a disconnect between the size of the African productive economy and the size and depth of our stock exchanges. You would see that there are still relatively few companies listed on our markets. If you recall, we’ve been talking about NNPC coming to the market for quite some time, particularly as a way of having a stronger representation of the oil and gas sector on the exchange. And a lot is happening within that space. We generate a significant portion of our revenue within the economy from the oil and gas sector. So, beyond companies like Seplat, Conoil, and Aradel, which has come into the market more recently, we still don’t have enough representation of that very important sector on the exchange.
Another issue is ownership structure. For many African companies, particularly large businesses, ownership is still heavily concentrated within families or founding groups. There is sometimes a perception that opening up these companies to the public would mean greater accountability and transparency, but it also means giving up some level of control, and that is one of the factors affecting the willingness of some businesses to list.
Secondly, we also need to look at the investor base. When you look at the number of active investors participating in the market, it is still relatively low. In Nigeria, for instance, we have less than 500,000 active CSCS accounts. And when you compare that with the size of the population and the size of the economy, you can see that there is still significant room for the investor base to expand. When you also look at other African countries and examine the statistics, particularly market capitalisation relative to GDP, you can see the same gap. Across many African markets, the average is around 83 percent, while for emerging economies it is around 61 percent, and globally, market capitalisation relative to GDP is almost 115 percent. So, there is still a significant gap that we’re seeing in that space. Liquidity is another major issue. We know that the NGX is doing its best, but beyond the traditional buy-and-sell structure, what really drives liquidity is having different financial instruments and market structures around the same securities. Investors should be able to short securities, build ETFs around them, and have different structures that allow them to participate in the market in different ways.
Guest
Executive Director, Kingsgate Advisors Institute
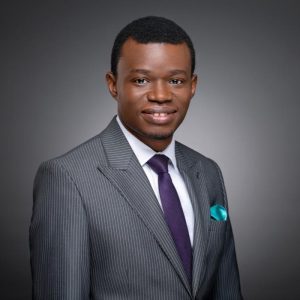
Chief Executive Officer, MDU Capital Limited